Published: October 11, 2026
Finance Minister Nirmala Sitharaman’s Singapore investment meetings have produced a public record of investor discussions, but the official announcement reviewed for this article does not provide a project-by-project register of resulting commitments, funding or implementation. That gap does not prove no deals were made; it means readers cannot yet verify outcomes from the announcement alone.
ClarityTimes.org’s review of the Ministry of Finance’s announcement and the October 10 meeting report found no consolidated public register connecting the reported engagement to verified investment amounts, Indian counterparties, and next milestones.
The next question is straightforward: which opportunities are progressing, and what evidence shows that they are?
What Does the Official Record Establish?
The official record confirms an investment outreach plan and a promise of government follow-up, but the announcement itself does not verify the investment outcomes of individual meetings.
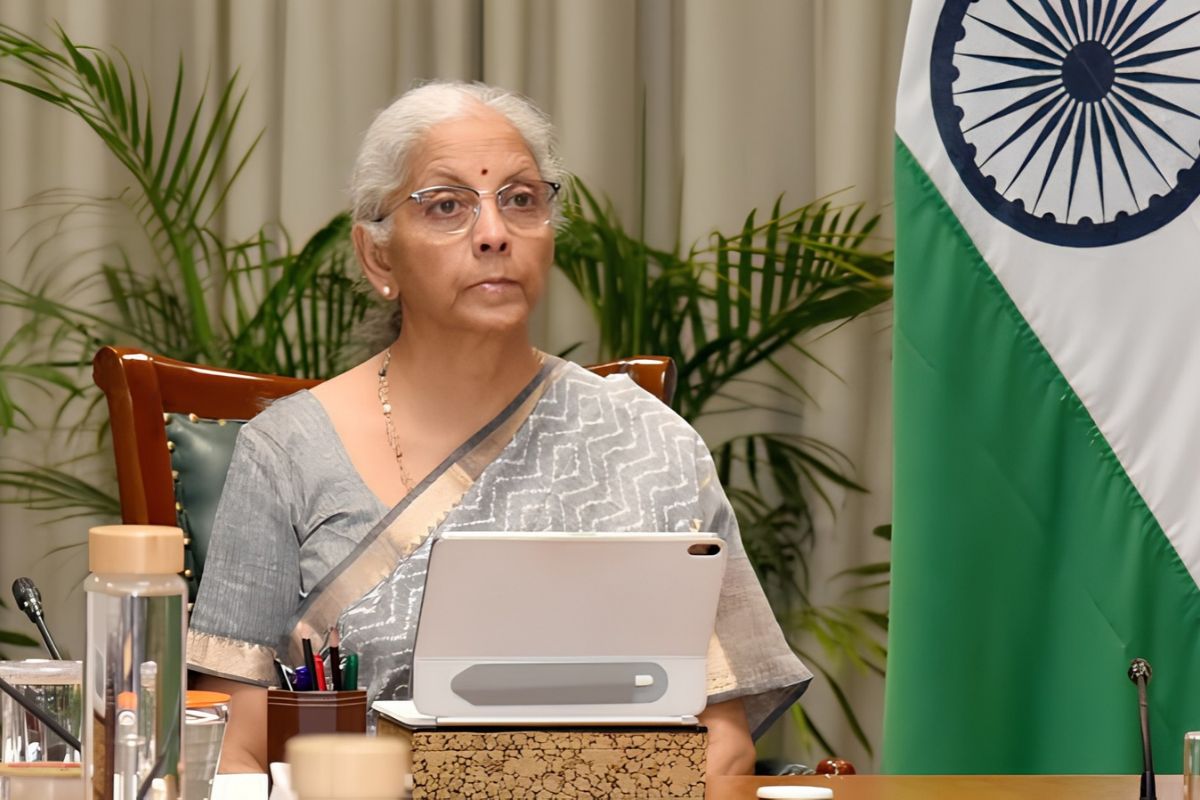
In its October 9 announcement, the Ministry of Finance said Sitharaman would meet senior executives from global investment funds, banks and businesses during her October 9–11 visit to Singapore. The listed institutions included the Government of Singapore Investment Corporation (GIC), Temasek Holdings, DBS Bank, Standard Chartered Bank, British International Investment and IHH Healthcare Berhad.
The announced discussions covered infrastructure, healthcare, financial services, renewable energy, manufacturing and other areas. The ministry also identified the National Investment and Infrastructure Fund (NIIF) and GIFT City as platforms that could facilitate greater participation by Singaporean capital.
The ministry said it would connect interested investors with Indian companies, financial institutions and state governments and help move identified opportunities forward.
Those are stated objectives, not proof of completed transactions.
The October 10 report by Moneycontrol described meetings with global executives and the investment sectors discussed. But the public material reviewed for this article does not provide a consolidated, project-level account showing which opportunities resulted in confirmed commitments, how much capital was involved or when the next milestones were due.
That distinction matters. The absence of a published register does not establish that no private agreements exist. It means the outcomes cannot be independently assessed from the announcements alone.
Why Aren’t Discussions the Same as Investment Commitments?
An investment discussion, a signed agreement, and money actually deployed are different stages of a transaction; a public tracker should never count them as equivalent.
An investment pipeline is a list of potential deals at different stages of development. It can include early conversations, proposals under review, and transactions approaching completion. Its existence does not mean the money has been invested.
A public tracker should separate at least five stages:
Discussions and introductions: Officials or investors confirm that a meeting took place, but no specific investment decision has been established.
Expressions of interest: An investor confirms interest in a particular opportunity, although negotiations, due diligence or approvals may remain outstanding.
Signed agreements: The parties have signed a document, such as a memorandum of understanding. Its terms and legal status must be checked before it is described as a binding investment commitment.
Investment commitments and financial close: A specific commitment is supported by documentation or authoritative confirmation. Financial close generally means the required financing agreements are in place, and applicable conditions have been met; it does not necessarily mean all funds have been disbursed.
Capital deployment and implementation: Records establish that money has been invested or deployed, followed by evidence of the project’s progress.
These stages cannot simply be added together to produce an investment total. A single project might appear first as a proposal, then as an agreement and later as a funded investment. Counting each appearance as a separate investment would inflate the result.
A credible Finance Ministry investment tracker should record the latest verified stage for each opportunity and update it when new evidence becomes available.
What Do Earlier India–Singapore Meetings Show?
Previous India–Singapore meetings show that official records can identify specific outcomes, although these outcomes should not be confused with private investment commitments.
According to Singapore’s Ministry of Foreign Affairs, the fourth India–Singapore Ministerial Roundtable, held on August 20, 2026, saw the exchange of two memoranda of understanding (MOUs) and one letter of intent (LOI).
The documents covered food safety, maritime heritage, and cooperation in telecommunications and broadcasting. The statement also said the ministers looked forward to further progress on the National Centre of Excellence for Advanced Manufacturing in Chennai, Tamil Nadu.
These are identifiable outputs with named institutions and documented subjects. They do not establish that Sitharaman’s October investment meetings generated equivalent agreements or financial commitments.
The example nevertheless offers a useful standard for public reporting. When an initiative produces a document or a defined next step, the record can identify it. When an investment remains under discussion, the record should say that instead of presenting the opportunity as completed business.
What Should a Finance Ministry Investment Tracker Disclose?
A public investment tracker should identify each verifiable opportunity, show its current stage, and explain what evidence supports that status.
The register would not need to publish confidential contracts. It could provide a concise, non-confidential summary with the following fields.
| Field | Information to publish |
| Investor | The participating fund, bank or company |
| Indian counterpart | The recipient company, project or government agency, where disclosure is permitted |
| Sector and location | The investment area and relevant Indian state or project location |
| Investment amount | The verified amount, labelled as proposed, committed, closed or deployed |
| Current status | The latest documented stage of the opportunity |
| Responsible agency | The department or organisation coordinating follow-up |
| Next milestone | The next recorded action or deadline, where one exists |
| Evidence and update date | A public document or attributable confirmation supporting the entry, plus the latest update date |
An unconfirmed amount should be marked as undisclosed or unverified, not estimated merely to make the register appear complete. The same rule should apply when the Indian counterparty or next milestone is unknown.
The register should also distinguish new opportunities linked to the Singapore meetings from investments already under development. Otherwise, an existing project could be presented as a result of the October outreach without evidence of a connection.
This approach would give readers a consistent way to compare what was announced with what subsequently happened. It would also allow journalists to investigate any material discrepancy between government statements, investor disclosures and company records.
Can Transparency Coexist With Commercial Confidentiality?
Yes. The government could publish a non-confidential account of investment progress without releasing sensitive negotiating terms or unfinalised proposals.
Companies may have legitimate reasons not to disclose negotiations before an agreement is finalised. Some discussions may also remain exploratory, while financing, regulatory approval or due diligence can delay a decision. Those possibilities should be acknowledged rather than treated as evidence of failure.
A tracker could still disclose the stage of a proposal, the responsible agency and the next recorded milestone where publication is permitted. It could also distinguish information that has not been disclosed from information that officials have not been able to verify.
Journalists seeking further evidence can use the Right to Information (RTI) Online portal, operated by India’s Department of Personnel and Training, to request existing records from central government public authorities. Relevant requests could cover meeting summaries, investor-introduction records, action-taken reports and follow-up correspondence.
Disclosure remains subject to applicable rules and exemptions. A request might produce records, partial information or a refusal. None of those outcomes, by itself, proves that an investment was or was not agreed.
The important distinction is between a lack of public disclosure and a verified absence of activity. Responsible reporting must not confuse the two.
What Should Happen Next?
The Finance Ministry should publish a post-visit update that separates verified investment outcomes from proposals that remain under discussion.
The first update could identify the opportunities that can be publicly confirmed, their latest documented status, and the agency responsible for follow-up. A later update could record changes in status, financial close, capital deployment or project implementation where evidence is available.
The reporting should also establish how many entries in the verified register have an identifiable Indian counterparty and a confirmed investment amount. Where those details are unavailable, the register should say so rather than imply that the record is complete.
This would not require every meeting to produce a transaction. Investment decisions depend on commercial assessments, financing conditions, due diligence and approvals. Some proposals will advance, while others will not.
It would, however, make the difference between an opportunity and an outcome visible.
Sitharaman’s Singapore investment meetings have established a public record of engagement and the government’s investment priorities. The next step is to establish which opportunities are moving forward, who is responsible for them, and what evidence confirms their progress.
The clearest measure of the meetings’ investment outcomes will not be the number of executives consulted, but the number of opportunities whose progress can be independently verified.
Frequently Asked Questions
Did Sitharaman’s Singapore meetings produce confirmed investments?
The official announcement reviewed for this article does not provide a project-by-project list of resulting investment commitments, funding, or implementation milestones. That does not mean no deals were made; it means the available public record does not establish the outcomes transaction by transaction.
What counts as an investment commitment?
A commitment needs evidence of a specific investment decision, supported by an authoritative confirmation or relevant documentation. An expression of interest, a signed non-binding memorandum, financial close, and actual capital deployment represent different stages and should be reported separately.
What should a public investment tracker include?
It should identify the investor, Indian counterpart where disclosable, sector, amount, current status, responsible agency, next milestone, and supporting evidence. Unconfirmed fields should be marked as undisclosed or unverified rather than filled with estimates.
How can journalists verify the outcomes?
They can compare the Ministry of Finance’s statements with investor disclosures, corporate filings and confirmation from the Indian counterparties. They can also request existing follow-up records through the official RTI Online portal, while recognising that some information may be withheld under applicable rules.