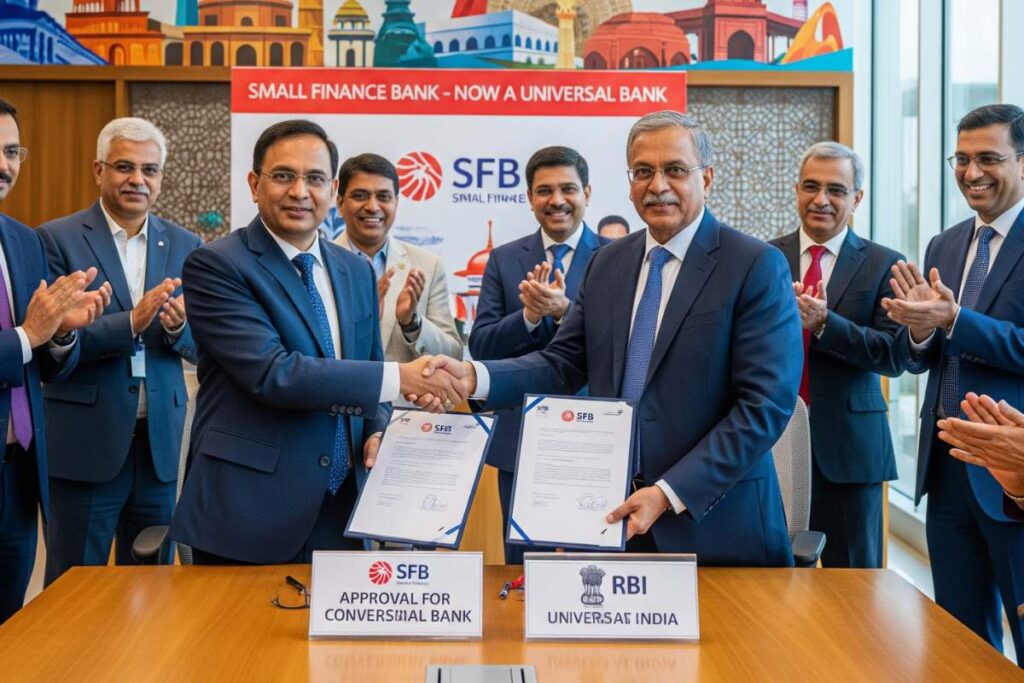
The Reserve Bank of India (RBI) regulatory pathway for Small Finance Banks (SFBs) transitioning to full-fledged Universal Commercial Banks marks a structural turning point in Indian banking. AU Small Finance Bank (AU SFB)—having integrated Fincare SFB and achieved the requisite net worth and asset quality thresholds—represents the primary test case of the RBI’s April 2024 transition circular. By transitioning from an SFB to a universal bank, the institution escapes the rigid 75% Priority Sector Lending (PSL) quota, unlocking a 40% standard mandate, removing the 50% cap on small-ticket loans (<₹25 lakh), and significantly lowering its blended cost of funds to compete directly against private-sector incumbents like HDFC Bank and ICICI Bank.
The RBI Universal Banking Transition Framework
In April 2024, the Reserve Bank of India (RBI) formalized the criteria allowing eligible Small Finance Banks to apply for transition into universal commercial banks under its “on-tap” licensing architecture. Unlike the differentiated bank licensing regime introduced in 2014–2015 to advance financial inclusion, a universal banking license removes operational restrictions on balance sheet sizing, product offerings, and customer segment caps.
To qualify for the universal transition, the central bank mandates rigorous prudential hurdles designed to insulate the financial system from systemic shocks:
- Track Record of Operations: Minimum five years of satisfactory operational performance as a scheduled Small Finance Bank.
- Net Worth Threshold: Minimum paid-up voting equity capital or net worth of ₹1,000 crore at the close of the preceding quarter.
- Asset Quality Norms: Gross Non-Performing Assets (GNPA) of no more than 3.0% and Net Non-Performing Assets (NNPA) not exceeding 1.0% over the trailing two consecutive financial years.
- Capital Adequacy: Minimum Capital to Risk-Weighted Assets Ratio (CRAR) of 15%, adhering to Basel-aligned supervisory benchmarks.
- Profitability & Listing: Audited net profit recorded in the last two financial years, alongside mandatory listing on recognized national bourses such as the Bombay Stock Exchange (BSE) and NSE.
- Diversified Shareholding: Absence of a single controlling individual entity, fulfilling RBI promoter shareholding dilution glidepaths.
Balance Sheet Arbitrage: SFB Restrictions vs. Universal Bank Freedom
The primary commercial impetus driving AU SFB’s transition application lies in structural balance sheet constraints. As a Small Finance Bank, regulatory directives severely curtail margin expansion and exposure limits. Foremost among these is the Priority Sector Lending requirement administered under the supervision of the Department of Financial Services (DFS) and RBI.
SFBs must allocate a staggering 75% of their Adjusted Net Bank Credit (ANBC) to priority sectors (agriculture, MSMEs, affordable housing, and weaker sections). In contrast, universal commercial banks operate under a far more manageable 40% ANBC mandate. This 3,500-basis-point difference forces SFBs into high-yielding but volatile micro-credit and unsecured SME exposures to meet targets, elevating provisioning costs during rural economic downcycles. The transition allows AU SFB to rebalance its loan book toward high-credit-rating corporate debt, supply chain financing, and syndicated credit facilities.
| Regulatory Parameter | Small Finance Bank (SFB) Mandate | Universal Commercial Bank Mandate | Strategic Impact on AU SFB |
|---|---|---|---|
| Priority Sector Lending (PSL) | 75% of Adjusted Net Bank Credit (ANBC) | 40% of Adjusted Net Bank Credit (ANBC) | Frees 35% of loan book for prime corporate and secured retail assets |
| Small Loan Portfolio Cap | ≥50% of loans must be ≤₹25 Lakh | No statutory portfolio size restrictions | Enables expansion into mid-market and large infrastructure working capital |
| Minimum Capital Adequacy (CRAR) | 15.0% Tier 1 + Tier 2 capital | 11.5% (including Capital Conservation Buffer) | Releases surplus regulatory capital for accelerated balance-sheet compounding |
| Foreign Exchange Operations | Authorised Dealer Category-II (Limited) | Authorised Dealer Category-I (Full) | Captures cross-border trade finance, remittance flows, and corporate hedging |
| Cost of Wholesale Funds | Higher risk spread on institutional deposits | Access to sovereign, PSU, and corporate treasury deposits | Estimated 30–60 bps reduction in blended cost of liabilities |
| Branch Distribution Mandate | ≥25% of branches in unbanked rural centres | Standard commercial banking branch rules | Optimizes branch network capex toward urban commercial corridors |
The Fincare Merger and Scale Economics
AU SFB’s balance sheet transformed significantly following its merger with Fincare Small Finance Bank in early 2024. The amalgamation added over ₹10,000 crore in assets, giving AU SFB an extensive footprint in southern India and establishing a pan-India franchise with over 2,400 touchpoints. However, the merger also incorporated Fincare’s microfinance (MFI) exposure, temporarily increasing gross credit costs during periods of rural asset quality stress.
Universal status provides AU SFB with the balance sheet agility required to absorb cyclical MFI shocks. By scaling up prime mortgage lending, commercial vehicle financing, and corporate payroll banking, the bank can construct a defensive deposit franchise. Furthermore, gaining an Authorised Dealer Category-I (AD Cat-I) license under the Foreign Exchange Management Act (FEMA) opens comprehensive trade services, documentary credits, and treasury foreign exchange trading—revenue streams historically reserved for full-scale commercial banks.
Interconnected Systemic Trends
AU SFB’s transition unfolds against broader shifts in India’s financial architecture. The central bank’s rigorous oversight of credit growth, unsecured personal loan risk weights, and electronic transaction networks has narrowed the regulatory arbitrage once enjoyed by non-banking financial entities. For deeper analysis of Indian banking rails and regulatory dynamics, examine our investigations into:
- Merchant payment economics and UPI MDR regulation shifts, examining how transactional fee structures impact commercial bank profitability.
- The micro-cash paradox and RBI currency management strategies, highlighting the institutional costs of physical branch operations.
- The MSME compliance burden and regulatory credit nudges, analyzing the real-world borrowing friction faced by informal enterprises.
Frequently Asked Questions
What are the eligibility criteria for an SFB to become a Universal Bank?
Under the RBI’s April 2024 circular, a Small Finance Bank must have a minimum operational history of five years, a net worth of at least ₹1,000 crore, CRAR of 15%, Gross NPA of 3% or lower, Net NPA of 1% or lower over the past two financial years, profitable operations, and an equity listing on a recognized stock exchange.
How does universal banking status impact AU SFB’s Priority Sector Lending requirements?
As an SFB, AU SFB is required to allocate 75% of its Adjusted Net Bank Credit (ANBC) to priority sector lending. Upon receiving full universal bank authorization, this requirement drops to the standard commercial banking target of 40%, giving the bank significant room to grow corporate and large-ticket commercial exposures.
Will AU SFB still be required to maintain 50% of its loans below ₹25 lakh?
No. The 50% small-ticket loan cap is an SFB-specific regulatory mandate. Once transitioned to a universal commercial bank, AU SFB will no longer be restricted by portfolio ticket-size caps, enabling it to compete directly for larger enterprise and syndicated loans.